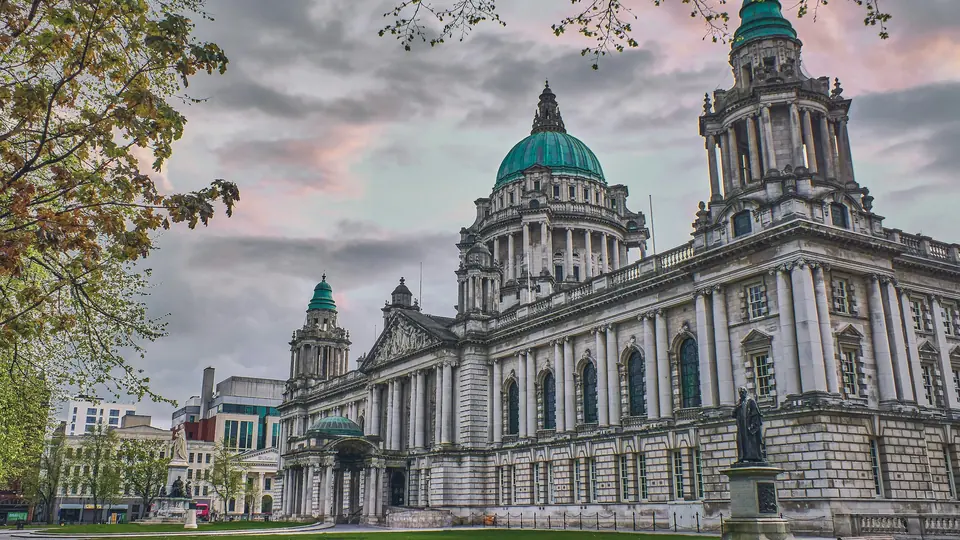
Bridging in Northern Ireland

Bridging loans in Northern Ireland

Far fewer bridging lenders lend in Northern Ireland than in Great Britain. Some have products written specifically for Northern Ireland, and a few lend across the whole UK. We compare the lenders on our panel that lend on property in Northern Ireland, so you can see the realistic options quickly.

On our panel, 8 lenders offer bridging in Northern Ireland, with rates from 0.67% a month, loans from £25,000 to £50m and terms up to 36 months (indicative).

See lenders for your deal →

What it can fund

  • Residential and semi-commercial purchases in Northern Ireland
  • Commercial property purchases and refinances
  • Auction purchases and quick completions
  • Light refurbishment and development exits
  • Land with planning, with lenders that take it

What lenders look at

  • The property type, location, value and condition
  • The loan size, as some lenders set higher minimums
  • The exit and the local sale or refinance market
  • Your experience and credit history
  • Whether you or your family will live in the property

Why the choice is narrower

Northern Ireland has its own legal system and land registration, with property registered either in the Land Registry or the older Registry of Deeds, and lenders need solicitors qualified in Northern Ireland. Many bridging lenders based in Great Britain do not lend there, which is why the panel is smaller.

On our panel, the lenders that lend in Northern Ireland include some with dedicated Northern Ireland products and some that lend UK-wide, mainly on larger loans. Loan to value limits, fees and minimum loan sizes can differ from the same lender's products in Great Britain, so it is worth comparing carefully.

Types of bridging available

Lenders on our panel that cover Northern Ireland consider residential and semi-commercial bridging, commercial bridging, land and some refurbishment and development exit cases. Some focus on smaller loans and will consider adverse credit, while others only lend from several hundred thousand pounds upwards.

Stamp Duty Land Tax applies to purchases in Northern Ireland, as it does in England, including the higher rates on additional residential properties. HMO licensing and landlord registration follow Northern Ireland's own rules, which refinance lenders will expect a let property to meet.

Arranging a bridge in Northern Ireland

With fewer lenders, a clear and complete case is especially important. Lenders will want details of the property, the purchase or refinance, any works, your experience, and evidence of the exit. Valuations are carried out by local surveyors, and the legal work by Northern Ireland solicitors.

We compare the lenders that lend in Northern Ireland on loan size, loan to value and terms, then approach those that fit. Instant Quotes lets you choose Northern Ireland as the location and shows the lenders that lend there, as a starting point. Final terms depend on each lender's valuation and checks.

If you or your family will live in the property

If the borrower is an individual or the trustees of a trust, and the property is, or will be, lived in by you or a close family member, the loan is a regulated mortgage contract with additional protections. We will tell you at the outset if that applies and how your case will be handled.

Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.

Questions

Bridging Loans in Northern Ireland: common questions

Can I get a bridging loan in Northern Ireland?

Yes, but fewer lenders lend there than in Great Britain. On our panel, a handful of lenders lend on property in Northern Ireland.

Are terms different from Great Britain?

They can be. Some lenders set lower loan to value limits, higher fees or higher minimum loans for Northern Ireland.

Is there a minimum loan size?

It varies. Some lenders consider smaller loans, while others lending UK-wide start from several hundred thousand pounds or more.

Does Stamp Duty apply in Northern Ireland?

Yes, Stamp Duty Land Tax applies to purchases in Northern Ireland, including higher rates on additional residential property.

Can I get development finance in Northern Ireland?

A small number of development lenders lend there. We can check the options for your scheme.

Lender reviews

Lenders we compare for bridging loans in Northern Ireland

Independent reviews of lenders that offer this type of finance. We are a broker and are not part of any lender listed. See all lender reviews.

Related finance

Bridge & Build Finance is a commercial finance brokerage service, not a lender. Finance is subject to status, lender criteria, valuation, underwriting and approval. Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
Ready to compare your options?

Get instant quotes from specialist property lenders today.

  • No credit search
    to view quotes
  • Free to compare
    multiple lenders
  • No obligation
    to proceed
Call Get Instant Quotes →
