What counts as non-standard
Standard construction usually means brick or stone walls with a tiled or slate roof. Non-standard covers a wide range of other methods, including:
- Precast reinforced concrete systems, many of which were designated defective under the Housing Defects Act 1984
- Steel frame and timber frame homes, some without an outer brick skin
- No-fines concrete and other poured concrete systems
- Prefabricated and system-built homes from the post-war period
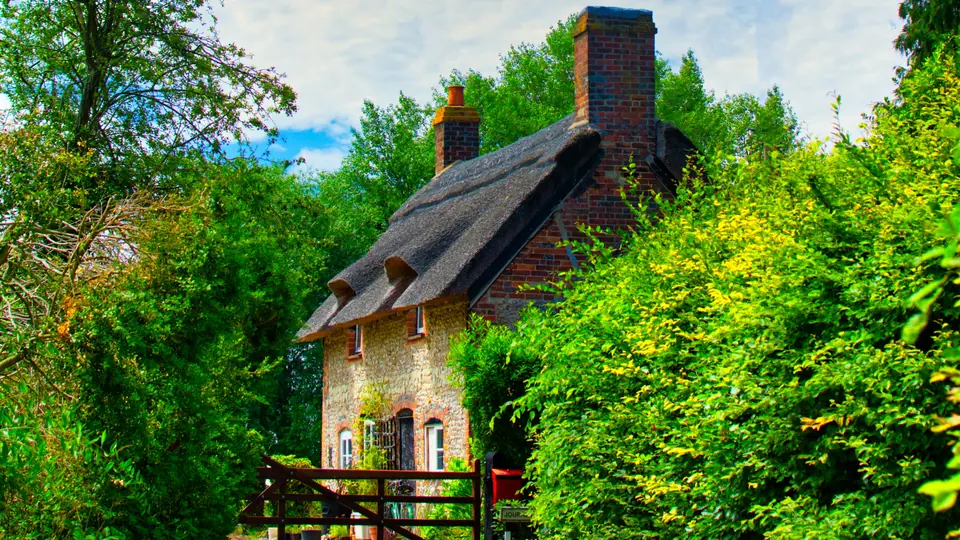
- Properties with non-standard roofs, such as thatch or flat roofs
Some types, such as modern timber frame with a brick outer skin, are widely accepted, while others are declined by most lenders unless repaired under an approved scheme.
Ex-local authority property
Ex-local authority houses are often of standard construction and treated like any other home. Ex-local authority flats can be more restricted, especially in high-rise blocks, deck-access blocks or estates where a high share of flats are still council owned. Some lenders reduce the maximum loan to value for ex-local authority flats, or for those above a certain number of storeys.
Cladding and fire safety on blocks of flats also affect lending. Lenders may ask for an external wall fire review, known as an EWS1 form, on taller or clad buildings.
How lenders on our panel treat it
Approaches vary. On our panel, some lenders list non-standard construction as acceptable, some consider it at a lower loan to value or with a rate loading, and some accept ex-local authority flats but exclude non-standard construction. Several other lenders exclude non-standard construction completely. Telling us the construction type at the outset lets us go straight to lenders that will consider it.
Planning the exit
The exit is the key question. If you plan to refinance, the mortgage lender must accept the construction type, so it is worth checking specialist buy-to-let or residential lenders early. If the property needs repair to become mortgageable, lenders will want an engineer's report, a costed repair scheme and, where available, a certificate from an approved scheme on completion.
We compare lenders on construction type, block and loan to value, then approach those that fit with a clear case. Instant Quotes lets you flag non-standard construction, as a starting point. Final terms depend on each lender's valuation and checks.
If you or your family will live in the property
If the borrower is an individual or the trustees of a trust, and the property is, or will be, lived in by you or a close family member, the loan is a regulated mortgage contract with additional protections. We will tell you at the outset if that applies and how your case will be handled.
Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.