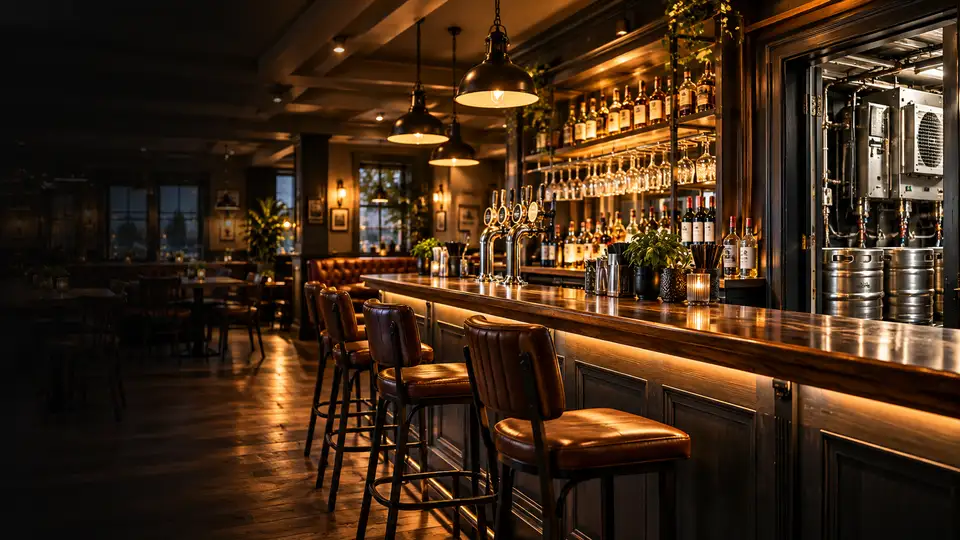
Pub and hotel bridging

Pub and hotel bridging loans

Pubs, hotels and other trading hospitality businesses are among the property types most often excluded by bridging lenders. A smaller group of lenders will consider them, usually at a lower loan to value than other commercial property. We compare those on our panel that state they consider pubs, hotels or trading-business property.

On our panel, 5 lenders offer bridging that considers pubs, hotels and trading businesses, with rates from 0.85% a month, loans from £100,000 to £50m and terms up to 24 months (indicative).

See lenders for your deal →

What it can fund

  • Buying a pub, hotel or guest house, including at auction
  • Refinancing hospitality property while a term loan is arranged
  • Buying a closed pub or hotel to reopen under new management
  • Buying hospitality property to convert to homes, with planning
  • Refurbishment before relaunching the business

What lenders look at

  • Whether the business is trading, and its accounts
  • The valuation basis: trading value or vacant possession value
  • The licence, location and condition of the property
  • Your experience in hospitality
  • The exit, such as a commercial mortgage, sale or conversion

Why hospitality is specialist security

A pub or hotel's value depends heavily on the business run from it. Valuers usually give a trading value, based on the earnings the business can sustain, and a vacant possession value, which can be much lower if the business closes. Many bridging lenders exclude pubs, bars, nightclubs and hotels for this reason, and others lend only against the vacant possession value.

On our panel, a few lenders state that they consider hospitality, pubs and hotels, or trading-business property generally, and some set lower loan to value limits for hospitality than for other commercial property, particularly on larger values.

Common situations

Bridging suits hospitality cases where speed or circumstances make a term loan impractical: a purchase at auction or from an administrator, a business that needs time to recover after a difficult period, a new operator taking over a closed pub, or a buyer who needs to complete before a specialist lender finishes its checks.

Some buyers plan to convert a pub or hotel to homes. Pubs are a sui generis use and conversion normally needs planning permission, and some pubs are listed as assets of community value, which gives the community a chance to bid before a sale. Lenders will look at the value with and without planning, and the plan to secure it.

What lenders look for

A strong application usually includes recent trading accounts and current figures, details of the premises licence, your experience or the experience of the operator, the condition of the building and any works needed, and a clear exit with supporting evidence.

The exit is often a commercial mortgage from a lender that specialises in hospitality, based on trading, or a sale of the business and property. For conversions, it may be development or refurbishment finance once planning is granted, or a sale with planning.

Arranging hospitality bridging

We compare lenders that consider pubs, hotels and trading property on valuation basis, loan to value and exit, then approach those that fit with a clear case. Instant Quotes lets you flag a pub, bar or nightclub, as a starting point. Final terms depend on each lender's valuation and checks.

If you or your family will live in part of the property, such as accommodation above a pub, the loan may be regulated depending on how much of the property is used as a home. We will tell you at the outset if that applies and how your case will be handled. Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
Questions

Pub and Hotel Bridging Loans: common questions

Do bridging lenders lend on pubs?

Some do, but many exclude them. On our panel, a few lenders state that they consider pubs, hotels or trading-business property.

Will the lender use the trading value?

It depends on the lender. Some lend against vacant possession value, which is usually lower than the trading value.

Can I bridge a closed pub to convert it into homes?

Yes, with lenders that consider it. Conversion normally needs planning permission, and lenders look at the value with and without it.

What is an asset of community value?

A listing that gives local community groups the chance to bid before certain sales. It can affect the timing of a purchase.

What is the usual exit?

A commercial mortgage based on trading, a sale, or development or refurbishment finance for a conversion.

Lender reviews

Lenders we compare for pub and hotel bridging loans

Independent reviews of lenders that offer this type of finance. We are a broker and are not part of any lender listed. See all lender reviews.

Related finance

Bridge & Build Finance is a commercial finance brokerage service, not a lender. Finance is subject to status, lender criteria, valuation, underwriting and approval. Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.
Ready to compare your options?

Get instant quotes from specialist property lenders today.

  • No credit search
    to view quotes
  • Free to compare
    multiple lenders
  • No obligation
    to proceed
Call Get Instant Quotes →
