How supported living property works
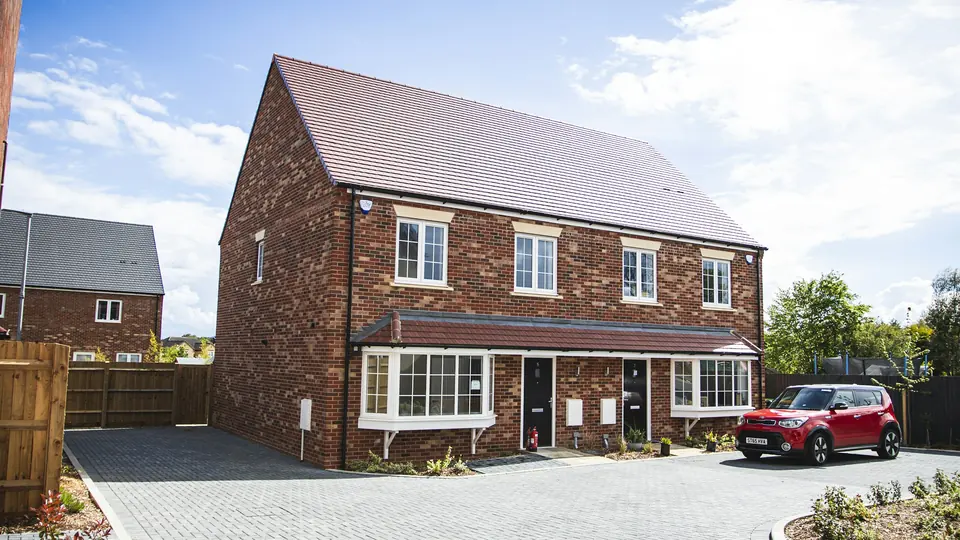
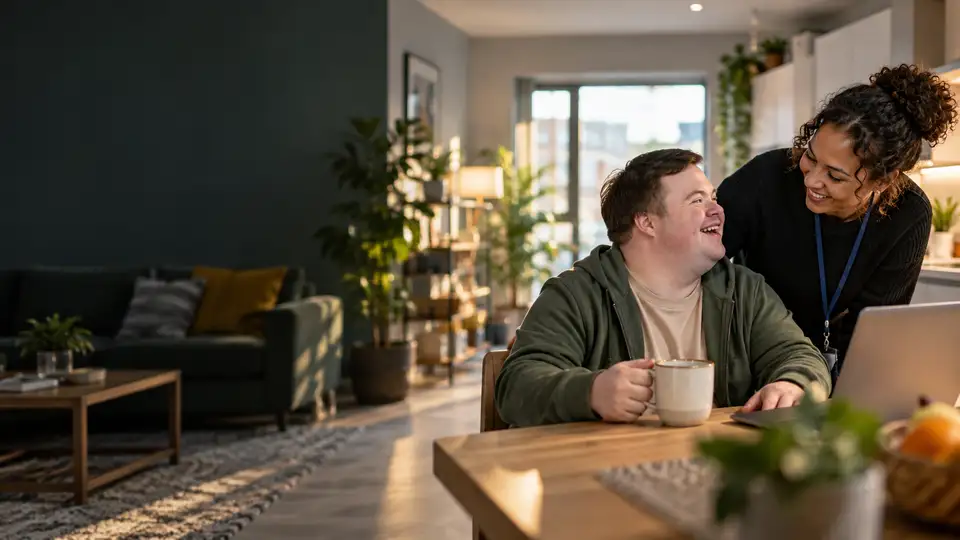
In a typical arrangement, an investor or developer owns the property and leases it to a housing provider, such as a registered provider or a charity. The provider manages the tenancies, and a separate care provider delivers support to the residents. Rents are often paid through housing benefit, which is why the provider and the lease structure matter so much to lenders.
Care providers are regulated by the Care Quality Commission in England, and registered providers of social housing by the Regulator of Social Housing. Lenders will want to know who each party is, how long they have operated and how the rent is funded.
Which finance fits
The right product depends on what you are doing:
- Buying a property that is ready to let. A bridging loan can complete the purchase while the lease is agreed and a long-term refinance is arranged.
- Adapting or converting a property. Refurbishment bridging can fund the purchase and the works, with the loan sized against the value after the works.
- Larger houses in multiple occupation. Shared supported living can share features with HMOs; see HMO bridging.
- New-build schemes. Development finance funds the land and construction, released in stages.
For schemes led by charities, social enterprises or community housing groups, our social and community housing page may be a closer fit.
What lenders look for
Lenders usually value supported living property in two ways: with the lease in place, and with vacant possession as ordinary housing. Many lend against the lower of the two, because the vacant value is what they could recover if the lease ended. Specialist adaptations can add cost without adding much to a vacant value, which is worth checking before you commit to the works.
A strong case includes the draft or signed lease, details of the housing and care providers, evidence of local demand from the council or commissioners, a costed schedule of works, and the planning and building regulations position. Changing the use of a building, or the number of people living in it, can need planning permission or licensing, so check with the local authority early.
The exit is usually a refinance onto a long-term commercial or investment loan once the lease is in place, or a sale to an investor. Lenders want to see that the refinance is realistic for the lease you have.
How we approach supported living cases
Lender appetite for supported living varies and is often decided case by case, depending on the lease, the providers and the property. We review the scheme, identify which lenders' criteria fit the property and the works, and approach them with a clear presentation.
Instant Quotes gives indicative figures based on the property and the loan, which is a useful starting point. Final terms depend on each lender's valuation, its view of the lease and its own checks.