Quick answer
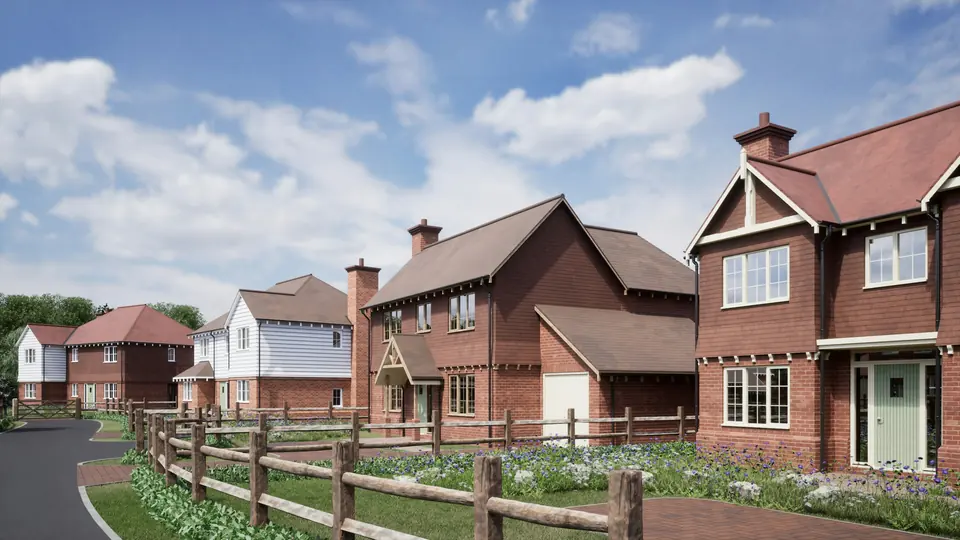
Yes. Many development lenders will fund the land purchase and the build in one facility, as long as the site has planning permission and the scheme stacks up. On 5 November 2026 The Intermediary reported that Atelier had completed a £12.6 million loan to Bruckland Developments for the land acquisition and ground up construction of 35 homes in Cowfold, a village in the Horsham district of West Sussex. The loan runs for 21 months at a loan to value of 70%, and the scheme includes 12 affordable homes. On a land and build loan the lender usually advances part of the site cost on day one and releases the build money in stages as a monitoring surveyor signs off the work. You still need to put in your own money, and the appraisal has to show a profit after finance costs.
What did Atelier fund in Cowfold?
According to The Intermediary and Property Reporter, the loan covers the following.
- Loan £12.6 million of development finance.
- Purpose buying the land and building the homes from the ground up.
- Term 21 months.
- Loan to value 70%.
- Homes 35 in total, made up of nine four bedroom detached houses, 14 three bedroom semis, 10 two bedroom semis and two one bedroom flats.
- Affordable housing 12 of the 35 homes.
Atelier's lending director Raj Hothi said the lender's focus is on understanding each opportunity and structuring funding that gives borrowers confidence and certainty. You can see the lender's terms on our Atelier Finance lender page.
How does a land and build loan work?
There are two parts. The first is a land advance, paid at completion of the purchase, which covers part of the site price. The second is the build money, released in stages against a schedule of works. Our guide to how development finance drawdowns work explains the stages, and our guide to monitoring surveyors explains who signs each one off.
Lenders set limits on both parts. They look at the loan against the site value, the loan against total costs and the loan against the finished value, and our guide to LTV and LTGDV shows how each is worked out. Interest is usually rolled up and repaid at the end from sales or a refinance. Our pages on ground up development finance and residential development finance cover the main options.
How much deposit do I need to buy land and build?
Most senior lenders expect you to fund part of the land and part of the costs yourself. Our guide to how much deposit you need for development finance sets out typical figures. Where the gap is too big, stretched senior development finance, mezzanine finance or a joint venture can reduce the cash you need, at a higher overall cost.
Lenders are competing for good schemes. Our report on Cambridge & Counties Bank's 80% loan to cost development finance shows how far some will go.
Do I need planning permission before I buy the land?
For a land and build loan, usually yes. Development lenders want an implementable planning permission before they release build money, as our guide on whether you need planning permission for development finance explains. If you want to buy a site before planning is granted, land finance or planning gain bridging can fund the purchase, then a development loan refinances it once permission is in place. Our guide to planning gain and land value shows how consent changes what a site is worth.
Planning rules are shifting too. Our reports on grey belt sites and planning reform and housing supply cover what has changed this year.
How do affordable homes affect the funding?
On larger schemes the council will often require a share of affordable homes through a planning obligation. GOV.UK guidance on planning obligations says these section 106 agreements can secure affordable housing on major residential developments, generally ten or more homes or a site of half a hectare or more.
Affordable homes are usually sold to a housing association at less than open market value, so they lower the gross development value. They can also give an early, more certain sale. Put the agreed price in your appraisal, and see our page on social and community housing finance for schemes sold to housing associations. Schemes of ten or more new homes may also pay the new building safety levy, which our report on Your First Home and the building safety levy covers.
What do lenders look for on a land and build deal?
- A clear appraisal. Land, build costs, fees, finance and a realistic gross development value. Our guide to writing a development appraisal sets out what to include.
- The right land price. Our guide to residual land value shows how to work back from the end value.
- Experience. Lenders like a track record, but there are routes for newer developers, set out on our first-time developer finance page and in our guide to what development lenders look for.
- A sensible structure. Many developers buy through a new company, as our guide to SPVs for property development explains, and larger sites can be built in phases.
- An exit. Show how the homes will sell, and plan a development exit loan in case sales take longer than the term.
What it means for your funding
Specialist lenders are still funding village housing schemes from the land up, even as private sales slow, as our report on whether new build sales are slowing shows. Borrowing has become dearer since the Bank of England raised Bank Rate to 4%, so allow for higher finance costs in your figures.
We are a whole of market development finance broker, so we search the market for lenders that fund the land and the build together for schemes like yours. Use Instant Quotes to see your matches in two minutes, try our calculators, or read how it works.
Common questions
Can I get one loan to buy land and build houses?
Yes. Many development lenders fund the land purchase and the build in one facility, provided the site has planning permission and the appraisal shows a profit after costs.
What loan did Atelier provide in Cowfold?
A £12.6 million loan for the land acquisition and ground up construction of 35 homes, over 21 months at a loan to value of 70%, according to The Intermediary and Property Reporter.
How is the build money released?
In stages against a schedule of works. A monitoring surveyor checks each stage before the lender releases the next payment.
How much deposit do I need for a land and build loan?
It depends on the lender and the scheme, but you will usually fund part of the land and costs yourself. Stretched senior, mezzanine or joint venture funding can reduce the cash needed.
Can I get a loan to buy land without planning permission?
Yes, through land finance or a planning gain bridge, which a development loan can refinance once permission is granted. Build money normally needs planning in place first.
Do affordable homes make a scheme harder to fund?
Not usually, but they lower the gross development value because they sell below market value. Put the agreed housing association price in your appraisal.
How long does a land and build loan last?
Long enough to build and sell the homes, agreed with the lender for each scheme. Atelier's Cowfold loan runs for 21 months.
This article reports news and published figures as at 6 November 2026. It is for general information only and is not legal, tax or financial advice. Bridge & Build Finance is a commercial finance brokerage service, not a lender. Finance is subject to status, lender criteria, valuation, underwriting and approval.
The weekly newsletter
Get articles like this by email
Our new articles on bridging, development finance, rates and the property market, and what each one means for your next deal.
- New articles every Friday
- What the news means for your deals
- Unsubscribe in one click