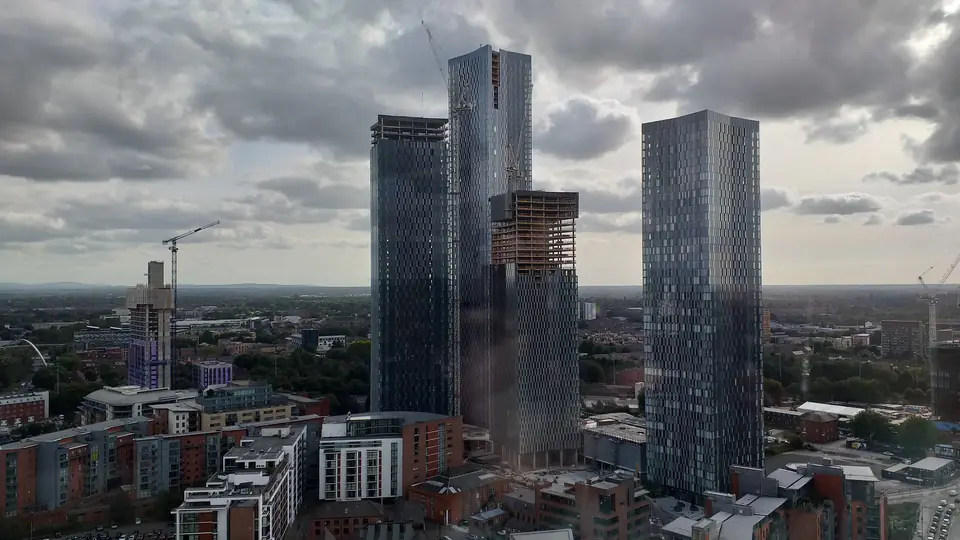
Manchester: housing targets and supply
Manchester City Council is the planning authority. Strategic housing numbers come from Places for Everyone, the joint development plan for nine Greater Manchester districts adopted on 21 March 2024, which sets 60,061 homes for Manchester between 2022 and 2039, about 3,533 a year, out of 175,185 across the plan area.
The council's housing strategy aims for 36,000 new homes, including 10,000 affordable homes, by 2032. In January 2026 it reported its best year yet: 2,993 homes delivered in 2025, 791 of them affordable, with 31% of the 36,000 target and 21% of the affordable target already achieved.
Developers here can also look at the Greater Manchester Housing Investment Loans Fund, run by the Greater Manchester Combined Authority, which offers stretch senior and mezzanine loans, with equity considered case by case, for housing schemes that are hard to fund elsewhere. It considers loans of £1 million to £30 million, usually for up to four years, and reports over £700 million committed to residential development. We are not part of it, but it can sit alongside or instead of the lenders we compare.
Sales values for a Manchester appraisal
Lenders size a development loan on the gross development value (GDV), backed by local sales evidence. In July 2026 the UK House Price Index put Manchester detached homes at £480,000, semi-detached at £330,000, terraced at £255,000 and flats at £195,000. Over the year, semi-detached prices rose 2.9% while flats were around the same.
As plain arithmetic, six semis at that average make a GDV of about £1.98 million, and at 60% of GDV, a common senior limit, would support around £1.19 million. New-build values often sit above second-hand averages, which is why lenders rely on a valuer's comparable new-build evidence.
For a build-to-rent or hold strategy, the rental figures matter more. In August 2026 a Manchester flat let for £1,147 a month and a semi-detached house for £1,496, with rents up 4.2% on the year; six semis let at that level would bring in roughly £107,712 a year gross.
Test your own figures with the residual land value calculator and the LTGDV and ROCE calculator.
England: tax, funding and building rules
A site bought in Manchester pays Stamp Duty Land Tax, and the appraisal also needs any Community Infrastructure Levy and section 106 costs that Manchester City Council sets for the scheme. Developers building five or more homes in Manchester can also look at Homes England, the government's housing agency, which is on our panel; see our Homes England review.
Development lenders for Manchester schemes
For Manchester, our panel has 49 lenders that offer development finance. The full list is below the questions, with links to our reviews. We check each lender's appetite for the exact address and property before putting your case forward.
Expect part of the land cost on day one, build costs released in arrears against monitoring surveyor reports, and rolled-up interest; if sales run late, a development exit loan can take out the build lender.
Development finance in Manchester: questions
How many homes is Manchester planning for?
Target: 36,000 homes by 2032. Places for Everyone adopted 21 Mar 2024. Manchester: 60,061 homes, 2022 to 2039.
What do homes sell for in Manchester?
July 2026 averages: £330,000 semi-detached, £195,000 for a flat, £480,000 detached (UK House Price Index).
What is the housing land supply position in Manchester?
2,993 homes delivered in 2025 (791 affordable).
Which council decides planning for a scheme in Manchester?
Manchester City Council. Places for Everyone adopted 21 Mar 2024.
