Listed building bridging

Bridging loans for listed buildings

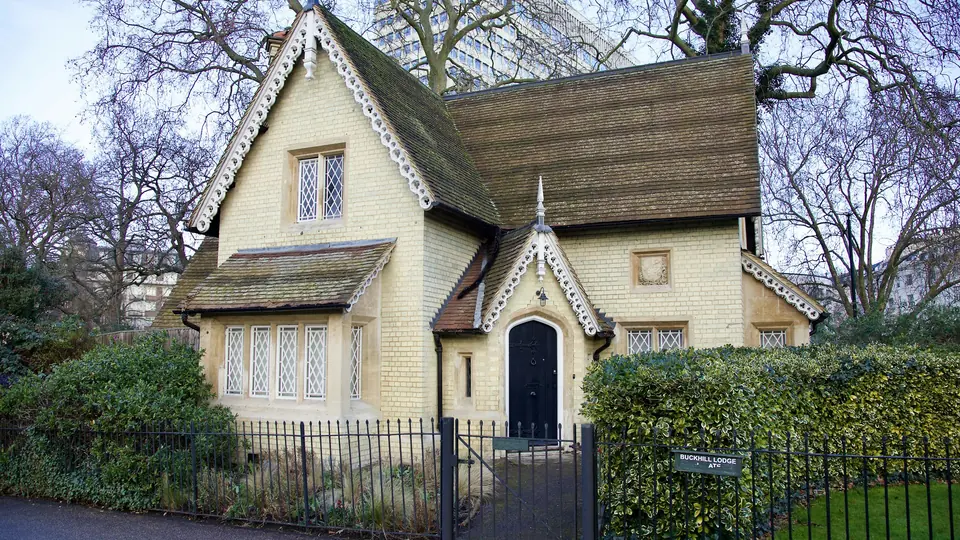
Listed buildings can be harder to finance, because works need consent, repairs cost more and some lenders exclude them. Many lenders consider Grade II property, while Grade I and other higher grades are usually considered case by case by underwriters or declined. We compare the lenders on our panel whose guides say they consider listed buildings.

On our panel, 8 lenders offer bridging that considers listed buildings, with rates from 0.53% a month, loans from £50,000 to £25m and terms up to 24 months (indicative).

See lenders for your deal →

What it can fund

  • Buying a listed home or building, including at auction
  • Breaking a chain on the purchase of a listed home
  • Repairs and refurbishment with listed building consent
  • Making a listed property mortgageable before a refinance
  • Refinancing a listed building while a longer-term loan is arranged

What lenders look at

  • The grade of listing and what the listing covers
  • Listed building consent for any works planned
  • The condition of the building and specialist repair costs
  • Saleability and mortgageability for the exit
  • Whether the property is, or will be, your home

Listing grades and lender appetite

In England and Wales, buildings are listed at Grade I, Grade II* or Grade II. Scotland uses categories A, B and C, and Northern Ireland uses grades A, B+, B1 and B2. Most listed homes are Grade II or the equivalent.

Lender appetite follows the grade. On our panel, several lenders consider Grade II property, sometimes with a slightly lower loan to value, while Grade I is commonly excluded and higher grades are considered case by case by underwriters. One lender on our panel excludes listed buildings entirely from a fast-track product. Checking this before applying avoids a decline after the valuation.

Works and consent

Listed building consent is needed for any works that affect the character of a listed building, inside or out. That can include replacing windows, removing walls, changing fireplaces or altering roofs. Carrying out unauthorised works is a criminal offence, and the owner can be required to reverse them, which is why lenders take consent seriously.

If the bridge is funding works, lenders will want to see the consent, a schedule of works prepared with the listing in mind and a contractor experienced in historic buildings. Specialist materials and methods, such as lime mortar and traditional joinery, cost more and take longer, so a realistic budget and contingency matter.

Valuation and the exit

Valuers will consider the condition of the building, the cost of maintaining it and the depth of the market for similar listed property. Unauthorised past alterations, structural movement or damp can affect both value and saleability.

If the exit is a refinance, check that the mortgage lender will accept the property and its grade. Some mainstream lenders are comfortable with Grade II homes in good condition but cautious about higher grades or unusual construction. If the exit is a sale, allow for a potentially longer marketing period.

Listed homes and regulated bridging

Many listed properties are bought as homes, for example where a buyer needs to complete before selling their existing house. If the borrower is an individual or the trustees of a trust, and the property is, or will be, lived in by you or a close family member, the loan is a regulated mortgage contract with additional protections. We will tell you at the outset if that applies and how your case will be handled.

Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.

We compare lenders on how they treat the grade, the works and the exit, then approach those that fit. Instant Quotes lets you indicate a listed building and shows lenders that consider it, as a starting point. Final terms depend on each lender's valuation and checks.
Questions

Listed Building Bridging Loans: common questions

Can I get a bridging loan on a listed building?

Yes. Several lenders on our panel consider listed buildings, most commonly Grade II. Grade I and higher grades are often considered case by case by underwriters or declined.

Do I need listed building consent for refurbishment?

For any works that affect the building's character, yes. Lenders will want to see consent before funding those works.

Will a listed building get a lower loan to value?

Sometimes. Some lenders reduce the maximum loan to value for listed property, particularly higher grades.

Can I use a bridge to buy a listed home before selling mine?

Yes, that is a common use. It is usually a regulated bridge, and we will tell you at the outset how your case will be handled.

Are listed buildings harder to sell or refinance?

They can take longer, and some mortgage lenders are cautious. Checking the exit lender's criteria early is important.

Lender reviews

Lenders we compare for listed building bridging loans

Independent reviews of lenders that offer this type of finance. We are a broker and are not part of any lender listed. See all lender reviews.

Related finance

Bridge & Build Finance is a commercial finance brokerage service, not a lender. Finance is subject to status, lender criteria, valuation, underwriting and approval. Your home or property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.

Ready to compare your options?

Get instant quotes from specialist property lenders today.

  • No credit search
    to view quotes
  • Free to compare
    multiple lenders
  • No obligation
    to proceed
Call Get Instant Quotes →